

Does the Premium Exxon Mobil Stock Valuation Mask Hidden Cash Flow Pressures?
 Analyze NVIDIA Like a Pro – Get Free 5-Page Executive Report & Insights
Exxon Mobil reported an astonishing $116B in quarterly revenue, yet the broader market remains curiously unconvinced by these top-line figures. With a historically elevated P/E ratio of 20x, we face a critical analytical puzzle regarding the true health of this energy giant. You might wonder if this premium Exxon Mobil stock valuation reflects a flawless operational pivot or if structural weaknesses are building beneath the surface. This article will dissect the fundamental data to help you understand the actual drivers of these returns and identify potential portfolio risks.
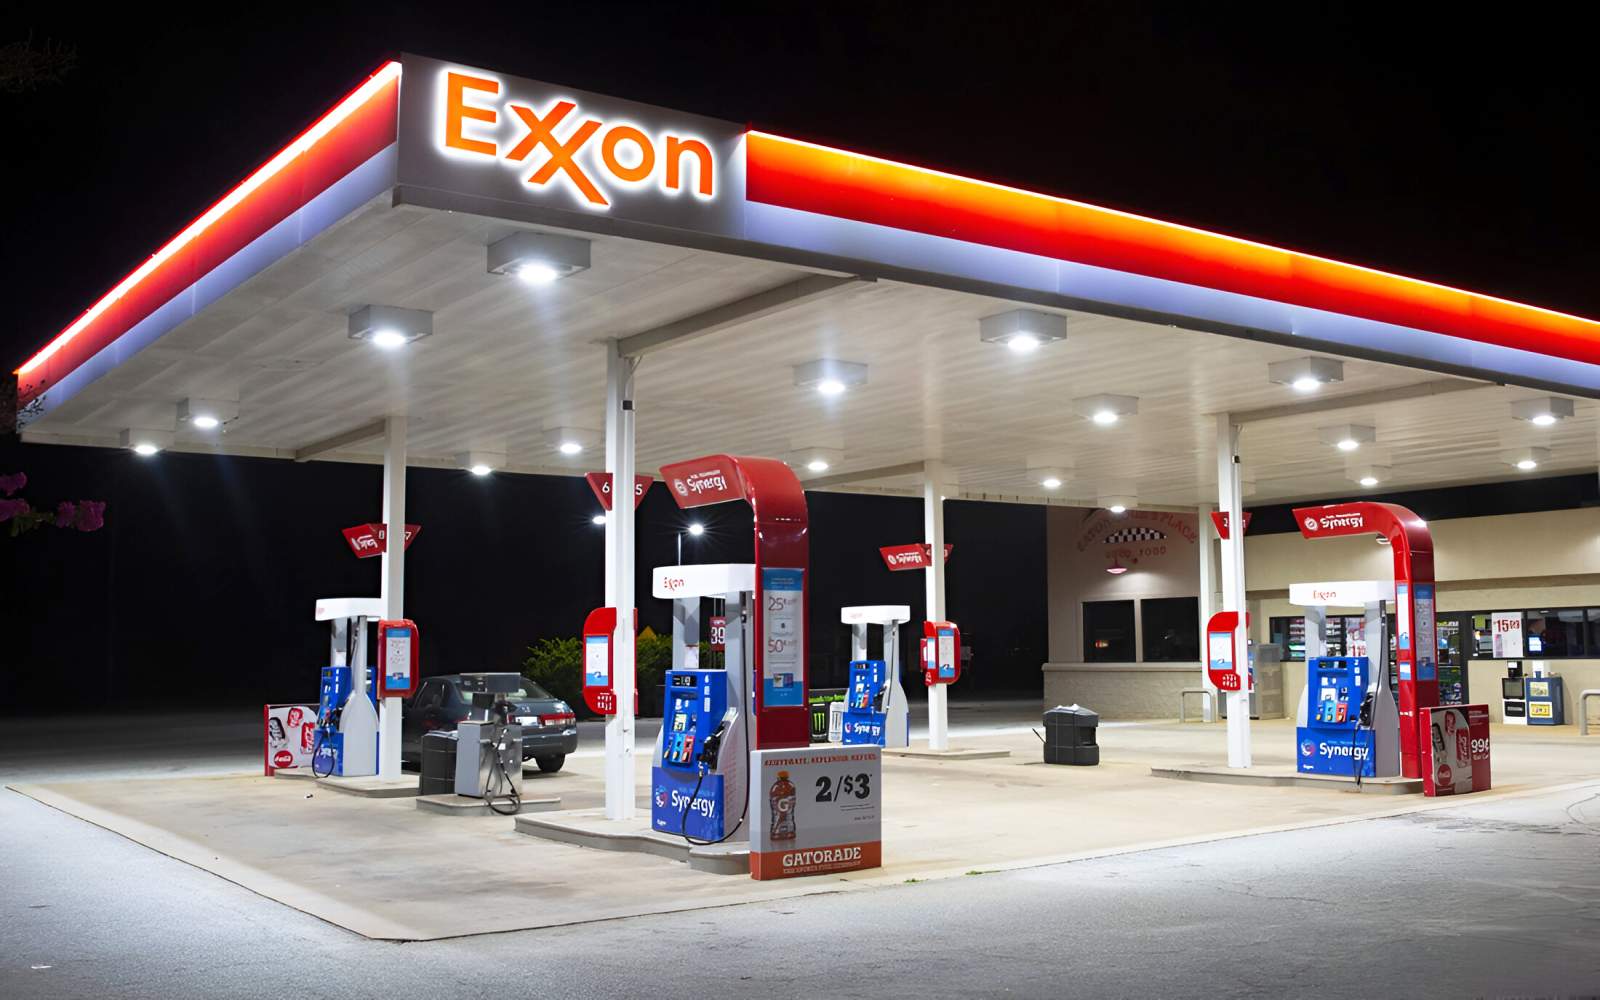 Photo: pexels.com
📌 Key Highlights
- Evaluating the Energy Transition Strategy Against Macro Realities
- Uncovering the Cash Flow Pressures Beneath the Revenue Beat
- Operating Margin Expansion Versus Diminishing Pricing Power
- Navigating the Liquidity Squeeze in a High-Rate Environment
- Assessing the Impact of Share Buybacks on Future Returns
Top-line metrics often mask the underlying mechanics of corporate profitability, especially when absolute net income reaches a massive $14.5B for the quarter. Market consensus suggests this earnings beat proves the company operates with absolute dominance, but factoring in a moderate 1.5% US GDP growth rate requires a deeper fundamental review. You must actively look beyond the headline numbers to determine if the premium you are paying today offers any margin of safety for tomorrow's uncertainties. The business is currently trading at a historically elevated P/E ratio of 20x, meaning investors are paying a steep premium for expected future performance.
This dynamic is exactly why your portfolio might feel stagnant despite reading broadly positive macroeconomic headlines regarding corporate profitability. You are essentially paying top dollar for past results rather than securing a solid foundation for future safety. You can easily check this phenomenon yourself the next time you review a major holding in your personal investment portfolio.
Evaluating the Energy Transition Strategy Against Macro Realities
The firm delivered a 42% revenue growth rate, which sounds exceptional until we examine the precise accounting mechanics driving this acceleration. A high valuation multiple inherently demands flawless execution across the board, leaving almost no room for unexpected operational errors. This brings us directly to a fascinating fundamental divergence in how the firm is generating these current returns. Understanding this concept is crucial, and we dedicate a lot of attention to it on the blog when discussing capital allocation. To contextualize this performance, we must evaluate the broader macroeconomic environment shaping the current energy transition strategy.
Consumer demand remains surprisingly resilient with the annualized US retail sales growth rate reaching 5%, while a current US Dollar Index value of 99 provides vital currency stability. The business is attempting to future-proof its model, specifically aiming to capture long-term electricity demand surges driven by massive AI data centers. Capturing this emerging AI-driven power demand requires massive upfront investments in physical infrastructure and strategic grid positioning. The transition phase demands heavy capital commitments, which introduces significant execution risk if global commodity demand fluctuates unexpectedly. Management must balance these capital-heavy projects against returning cash to shareholders, representing an increasingly delicate high-wire act.
If the transition costs exceed historical estimates, the current multiples will compress rapidly as forward earnings estimates are inevitably revised downward. These ambitious expansion plans must also navigate a complex monetary landscape that actively penalizes debt-funded growth initiatives. The broader macroeconomic environment currently features a stubborn US inflation rate of 3.4% alongside elevated borrowing costs. The federal funds rate sitting between 3.75% and 4% makes funding heavy physical infrastructure significantly more expensive than in previous decades. This elevated cost of capital forces management to rely heavily on internal cash generation to fund their strategic vision.
Uncovering the Cash Flow Pressures Beneath the Revenue Beat
To fully grasp why specific strategic shifts are happening, we need to look at a seemingly unrelated metric sitting quietly on the corporate balance sheet. Accounts receivable unexpectedly expanded by nearly 45%, reaching well over $60B during the most recent financial measurement period. General market sentiment largely ignores these working capital fluctuations when absolute net income remains historically high, yet this receivables jump notably outpaces the 42% revenue growth rate. This specific metric divergence suggests the corporation may be extending significantly looser credit terms to buyers to artificially sustain sales volumes.
Think of it this way: if customers aggressively delay payments for heavy physical products, this tactical revenue recognition strategy creates an invisible cash flow gap. The true driver of this current valuation is tied up in uncollected bills rather than actual cash deposited securely in the operating bank account. This introduces a specific market friction, as record paper profits are not seamlessly converting into deployable capital for immediate reinvestment. Recognizing these hidden cash flow pressures is essential for protecting your capital during volatile market cycles.
Operating with billions in uncollected receivables fundamentally changes the risk profile of a business that requires constant capital reinvestment. When paper profits fail to materialize into liquid cash, management loses the tactical flexibility needed to acquire distressed competitors. This is a topic we expand on in our other guides covering advanced balance sheet forensics and risk mitigation.
Key factors driving this working capital divergence:
- Wholesale buyers are demanding longer payment windows to manage their own elevated inventory holding costs.
- The company is utilizing aggressive credit extensions to maintain market share against agile global competitors.
- Delayed cash conversion cycles are quietly draining internal liquidity reserves despite record top-line revenue recognition.
- International currency controls are artificially extending the time required to repatriate overseas physical product sales.
- Rising borrowing costs are forcing downstream partners to rely on supplier financing to fund daily operations.
Operating Margin Expansion Versus Diminishing Pricing Power
A closer examination of profitability metrics reveals a clear disconnect between bottom-line efficiency and top-line market dominance. Operating margin recently expanded to an impressive 16.7%, a figure primarily driven by strict internal cost-cutting initiatives rather than organic expansion. Standard financial models often assume management possesses exceptional pricing power across global energy markets, but we must weigh this heavily against a trailing twelve-month gross margin that slightly decreased to 23.94%. This shrinking gross profitability reveals a very different fundamental reality about the competitive moat surrounding the underlying business. The enterprise is effectively squeezing out profits through internal operational discipline rather than possessing ultimate pricing authority over buyers.
When a company cannot dictate favorable terms at the gross level, future earnings momentum relies entirely on keeping operational expenses perfectly flat. If operating expenses creep upward due to inflation, this lack of top-tier pricing power could severely threaten future bottom-line profitability. Grasping this nuanced margin dynamic helps you look at quarterly financial reports in a completely new and highly analytical light. You realize that relentless cost-cutting eventually hits a mathematical floor, after which organic revenue growth must carry the burden. Without the ability to raise prices aggressively, the firm remains highly vulnerable to unexpected supply chain shocks or raw material inflation.
The current operating margin expansion is a temporary victory that ultimately masks the slow decay of structural pricing leverage. Investors must acknowledge that defending these profit margins will become increasingly difficult as the global energy transition accelerates. Competitors are heavily subsidizing green energy alternatives, putting immense downward pressure on traditional fossil fuel pricing structures across international markets. Once the easy structural costs are fully optimized, maintaining that 16.7% operating margin will require a miraculous stabilization of global commodity prices.
Navigating the Liquidity Squeeze in a High-Rate Environment
The margin pressures inevitably lead us directly to the single most vulnerable part of the entire corporate balance sheet. The total debt to equity ratio sits at a highly conservative 12.1%, painting a surface-level picture of fundamental financial strength. Current market sentiment implies this relatively low leverage makes the firm an impenetrable fortress against economic downturns. However, actual cash and short-term investments dramatically decreased by over 32% year over year, telling a vastly different story. This rapid cash drain pushed the critical quick ratio down to a cautionary 0.85 during the most recent measurement period.
Having liquid assets barely cover immediate short-term obligations means less immediate liquidity to maneuver through sudden supply disruptions or regional policy shifts. Operating with a quick ratio below one effectively signals an emerging liquidity squeeze that restricts opportunistic capital deployment. Management is actively burning through on-hand cash, forcing the company to rely heavily on future operating cash flows to fund daily activities. This specific liquidity squeeze matters immensely because of the heavy physical infrastructure the firm is building out across the globe. The company is actively funding massive underground carbon storage facilities along the US Gulf Coast to diversify future revenue streams.
Balancing these capital-heavy projects, including providing commercial carbon capture services, against maintaining a healthy balance sheet is a monumental task. The elevated interest rate environment makes external debt funding for these long-term green initiatives completely unpalatable from a return on investment perspective. As the liquidity buffer steadily shrinks, the company's ability to absorb unexpected macroeconomic shocks diminishes exponentially. A sudden collapse in global energy demand would immediately threaten their ability to service these massive short-term operational liabilities. If the accounts receivable fail to convert into cash promptly, this increasingly tight liquidity position could easily trigger a sudden operational crisis.
Assessing the Impact of Share Buybacks on Future Returns
To appease current institutional investors, the firm recently executed an aggressive share reduction program utilizing their dwindling cash reserves. Management successfully shrank the outstanding float by exactly 157M shares in an attempt to manufacture sustained equity value. A close review clearly shows how reducing the share count artificially boosts earnings per share, helping solve the frustration of slow organic growth. While this rewards existing shareholders immediately, it fundamentally starves the core business of capital desperately needed for future infrastructure projects.
These massive share buybacks are notably offset by a current dividend yield of 2.52%, providing a modest income floor for retail investors. However, using precious liquid capital to retire equity while simultaneously facing a 32% cash drain represents a highly controversial capital allocation strategy. You must ultimately decide if you prefer immediate EPS engineering or long-term financial resilience when building your personal investment portfolio.
Alternative scenarios regarding the current valuation trajectory:
- The firm successfully monetizes its carbon capture investments, creating a high-margin revenue stream that rapidly replenishes depleted cash reserves.
- Global AI data center expansion triggers an unprecedented electricity demand shock, allowing the company to regain substantial top-line pricing power.
- Macroeconomic conditions cool significantly, forcing buyers to default on their delayed payments and triggering a severe working capital crisis.
- Persistent inflation keeps interest rates elevated, making future infrastructure projects unprofitable and forcing a sudden dividend reduction.
The diligent long-term value investor must recognize that the current valuation offers a very narrow margin of safety right now. The business remains a cash-generating giant securing vital energy infrastructure globally, but executing perfectly on all fronts is statistically improbable. Paying a premium multiple today leaves little room for error if expansion stalls or if transition costs massively exceed initial expectations. You must weigh the undeniable operational discipline against the very tangible execution risks presented by a decaying balance sheet.
Ultimately, the reliance on financial engineering to mask fundamental gross margin deterioration should give conservative investors serious pause. The strategic decision to prioritize share reductions over maintaining robust liquidity buffers indicates a management team highly focused on short-term equity performance. If the macro environment shifts unfavorably, this lack of financial flexibility will immediately penalize those who bought at the top of the cycle. True wealth generation requires identifying sustainable cash flows rather than chasing artificially inflated per-share metrics during peak market exuberance.
Institutional money managers are already beginning to scrutinize these exact balance sheet vulnerabilities behind closed doors. You must carefully decide whether the surface-level revenue beat provides enough compensation for the underlying deterioration in gross profitability and corporate liquidity. Navigating these conflicting financial signals is what ultimately separates successful long-term capital allocators from casual retail investors who merely chase headline numbers.
Conclusion
We started this analysis by asking if the premium Exxon Mobil stock valuation reflects a flawless transition or masks underlying financial vulnerabilities. The fundamental data clearly indicates that while the company displays immense operational discipline, the surface-level revenue and profit beats are largely priced into the stock. Shrinking gross margins, ballooning uncollected bills, and a rapidly declining cash balance introduce tangible execution risks that you cannot afford to ignore. Management is brilliantly cutting costs to elevate the equity, but operating with diminishing immediate liquidity threatens the long-term sustainability of this premium multiple.
Analyze Nvidia Like a Pro – Get Free 30-Page Professional Report & Insights
Our mission is to provide credible, practical knowledge that helps you make better financial decisions. Each post on this blog is another building block towards your success. We encourage you to read on – the best investment you can make is in your own knowledge.
Disclaimer
This article is provided for informational and educational purposes only and does not constitute investment, financial, or trading advice. The content reflects the author’s opinions and analysis based on publicly available information and does not take into account your individual financial situation, objectives, or risk tolerance. MarketVectors.Pro and its affiliates do not make any representation or warranty as to the accuracy, completeness, or timeliness of the information presented and shall not be held liable for any investment decisions, losses, or damages resulting from the use of this content. Always conduct your own research and consider consulting a qualified financial professional before making any investment decisions. For more details, please review our full disclaimer.
 Did you find this article useful and informative? If it helped you better understand the topic, consider leaving a comment and sharing it with others who might benefit from it. The author is not a licensed financial advisor, and the content is intended for educational purposes only. You can learn more about our mission and team on our about us page. – The MVPro Team



Comments