

Micron stock analysis: Is massive growth hiding a cyclical trap?
 Analyze NVIDIA Like a Pro – Get Free 5-Page Executive Report & Insights
Reporting an astonishing $23.86B in total revenue, Wall Street is simultaneously thrilled and terrified that this explosive growth will eventually trigger a catastrophic oversupply. Our comprehensive Micron stock analysis will uncover whether the company is building an impenetrable empire or walking directly into a dangerous cyclical trap. As a savvy investor, you will gain critical insights into the underlying financial mechanics that could either wipe out early buyers or generate massive long-term wealth. Let us dive deep beneath the surface to explore the complex reality of this unprecedented technology hardware cycle.
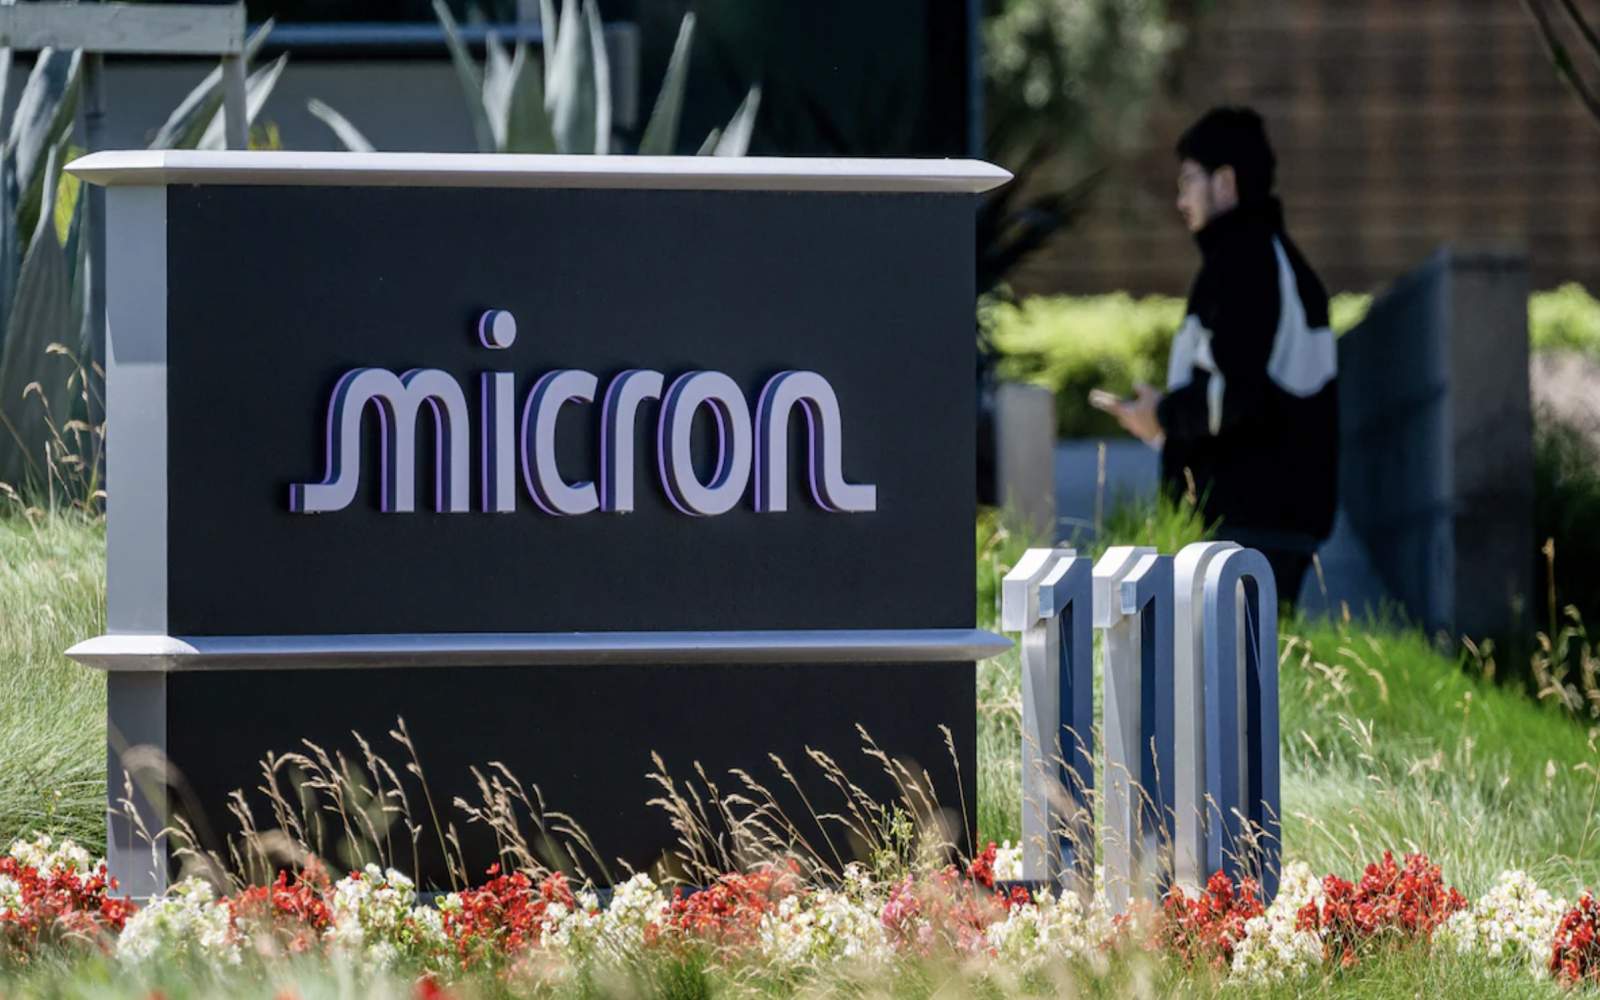 Photo: pexels.com
📌 Key Highlights
- Micron stock analysis: The illusion of infinite semiconductor investment opportunities
- Capital expenditures and navigating the memory sector cyclical trap
- Evaluating the Micron financial fortress and balance sheet strength
- Tech stock valuation, earnings, and advanced value investing strategies
- International headwinds and the final verdict on value investing
Understanding market cycles is a fundamental skill for anyone looking to build a resilient and highly profitable investment portfolio over the long term. This hyper-growth establishes a perilous baseline for your portfolio because future expectations are now wildly detached from established historical norms. This is a topic we expand on in our other guides, where we teach readers how to spot early warning signs in momentum stocks when top-line growth accelerates too fast.
Micron stock analysis: The illusion of infinite semiconductor investment opportunities
Look closely at the stunning 196% year-over-year revenue growth reported during this most recent and highly scrutinized financial quarter. Reaching exactly $23.86B in total revenue signals quite clearly that the enterprise is riding an unstoppable structural shift in the memory sector. Revenue simply measures the total money brought in by sales before any operating expenses or taxes are officially deducted from the ledger. We must carefully examine underlying profitability to truly grasp why this specific revenue peak remains incredibly fragile despite the bullish media narrative.
During this truly unprecedented economic cycle, the gross margin metric hit an astonishing 74.4% across their global product portfolio. Gross margin represents the crucial percentage of revenue left over after paying the direct costs of manufacturing goods, and hitting 74.4% is exceptionally rare. Mainstream financial media excitedly calls this a true margin miracle, loudly celebrating the corporation for demonstrating absolute pricing leverage over enterprise buyers. Yet, this overly positive narrative completely ignores the harsh fundamental reality of peak pricing in a notoriously cyclical hardware industry.
Average selling prices jumped over 100% in a single market cycle, creating a massive financial burden for major corporate customers. Extended periods of extreme pricing power inevitably prompt major customers to aggressively seek out and fund alternative storage technologies. For your dynamic investment portfolio, the core fundamental analysis lesson is that a 74.4% gross margin is rarely a sustainable long-term plateau, and any sequential contraction will immediately signal that this rare pricing leverage is evaporating.
Capital expenditures and navigating the memory sector cyclical trap
This terrifying margin contraction possibility brings us directly to the massive elephant in the room regarding their aggressive future growth plans. Corporate management recently decided to unleash a staggering $25B capital expenditure program designed to secure their dominant market position. Capital expenditure formally represents the vital funds a business uses to acquire, completely upgrade, and maintain physical assets like advanced fabrication plants. Analysts broadly view this $25B capital expenditure as a necessary fortress-building exercise to absolutely dominate future artificial intelligence memory requirements.
Despite the obvious strategic necessity, this colossal financial deployment carries severe execution risk that could fundamentally derail the entire corporate trajectory. Success in this endeavor strictly requires flawless facility construction timelines alongside completely uninterrupted data center spending from their largest global clients. If global technology demand slightly falters, these expensive leading-edge fabs could rapidly transform into underutilized physical assets bleeding precious corporate capital. As a smart investor, you must relentlessly watch their specific $25B capital expenditure guidance over the highly unpredictable coming quarters.
Sound investing strategy constantly dictates that securing future market share is entirely meaningless if it inadvertently triggers a devastating cyclical overbuild. Building this monumental infrastructure inherently requires immense amounts of liquid cash to ensure continuous operations without crippling external debt. A massive $1.8B fab acquisition cost recently highlighted just how expensive expanding this physical asset base has become, which continuously raises the denominator in critical profitability metrics that institutional investors monitor.
Evaluating the Micron financial fortress and balance sheet strength
Generating an impressive $20.3B in operating cash flow over 6 months certainly provides this tech giant with a phenomenal financial fortress. Operating cash flow precisely measures the actual cash brought in by regular daily business operations before any capital investments are made. This extreme liquidity generously allows the company to self-fund its massive expansion without relying on expensive external financing during periods of global uncertainty. Locking up $20.3B in operating cash flow into highly capital-intensive projects heavily tests the ultimate patience of retail investors.
The clear trade implication here is that this aggressive cash conversion must eventually yield superior long-term dominance, or it simply finances an industry-wide supply glut. For your active portfolio, this specific management team must continually prove this massive cash hoard is a strategic weapon rather than a margin-crushing dead weight. Understanding this concept is crucial, and we dedicate a lot of attention to it on the blog when discussing capital allocation strategies for highly cyclical hardware businesses.
By aggressively prepaying exactly $4.19B in standing debt principal, corporate management quietly and effectively bulletproofs the entire balance sheet against rising interest rates. Wall Street predictably interprets this massive debt reduction as highly prudent risk management coming directly from a team of seasoned executives. Intentionally pushing the debt-to-equity ratio down to exactly 0.14 actually signals a highly defensive and incredibly cautious forward-looking posture. The debt-to-equity ratio formally compares total liabilities to shareholder equity to clearly show exactly how much debt finances corporate assets.
This pristine and carefully managed balance sheet reveals that corporate leaders are actively preparing for severe market volatility and brutal future pricing pressures. The key investing strategy lesson here is that a deeply conservative 0.14 debt-to-equity ratio is absolutely necessary to survive massive capital outlays. Without this incredibly defensive posturing, the organization would risk facing immediate financial ruin during the next inevitable industry downturn. This rigid liquidity management heavily influences how they handle periods of intense global uncertainty while simultaneously expanding physical capacity.
Before moving into our profitability metrics, it is vital to review the precise components that make up this incredible defensive strategy. Management has clearly defined a set of financial priorities to ensure they navigate the dangerous waters of cyclical memory demand. You should carefully consider these exact strategic maneuvers when attempting to model their future cash flow generation capabilities. Several distinct corporate actions actively highlight their deeply entrenched conservative operational philosophy.
- Generating $20.3B in operating cash flow provides the necessary ammunition to self-fund massive international expansion plans.
- Prepaying $4.19B in existing debt completely insulates the corporate balance sheet from wildly fluctuating interest rates.
- Maintaining a strict 0.14 debt-to-equity ratio effectively guarantees survival during periods of unexpected revenue contraction.
- Amassing $14.59B in short-term investments creates an impenetrable buffer against sudden macroeconomic shocks.
Most seasoned financial analysts correctly view this vast liquidity pool as the ultimate safety net during prolonged periods of intense global uncertainty. Yet, actively amassing $14.59B in cash and short-term investments while deliberately executing only $650M in share repurchases highlights a truly glaring internal contradiction. When highly informed corporate insiders aggressively hoard immense cash instead of aggressively buying back their own stock despite record profits, your portfolio should inherently prepare for imminent market turbulence.
Tech stock valuation, earnings, and advanced value investing strategies
Speaking directly of shareholder rewards, this highly defensive corporate posture radically impacts the bottom-line financial numbers you care about the most. The sudden and massive leap to $12.07 in diluted earnings per share transforms the organization from a cyclical hardware vendor into an elite profit engine. Diluted earnings per share formally shows a company's total overall profit divided by all outstanding shares including convertible financial instruments. Eager novice investors immediately see this bottom-line explosion and falsely assume the stock valuation will simply compound forever without interruption.
Unfortunately, hitting exactly $12.07 in diluted earnings per share instantly recalibrates sophisticated institutional valuation models across the entire financial sector. This elevated benchmark completely strips away any remaining margin of safety for future earnings misses during the upcoming fiscal quarters. It unfortunately means you are permanently trapped in an expectation loop where only flawless quarterly execution will prevent brutal stock corrections, putting immense pressure on how the company treats its loyal long-term shareholders.
Despite generously declaring a highly publicized dividend increase, the actual capital return profile remains remarkably tight and highly restrictive for retail investors. The incredibly low 1.4% dividend payout ratio fully exposes a remarkably stark capital allocation reality hiding in plain sight. The dividend payout ratio explicitly tells you exactly what percentage of corporate net income is distributed directly to loyal shareholders in cash dividends. Management is deliberately hoarding its unprecedented cash windfall to fund physical capacity expansions, effectively prioritizing global infrastructure dominance over any immediate shareholder gratification.
Retail investors actively looking for substantial ongoing yields will suddenly find themselves entirely subordinated to the massive global expansion mandate. To truly understand how they fund this mandate, we must deeply dissect the highly lucrative Cloud Memory segment revenue data. This specific division recently reached an astounding $7.75B in quarterly revenue, powerfully showcasing the undeniable market momentum currently driving high-bandwidth memory adoption. However, relying so heavily on exactly $7.75B in segment revenue inherently creates a massive single point of failure tied directly to just a few powerful data center operators.
Mastering true value investing requires actively acknowledging that these highly concentrated operational liabilities can erode core profitability incredibly fast. Evaluating sector concentration risk is an essential practice that protects your underlying principal during violent technology hardware selloffs. You must actively monitor several distinct variables to successfully navigate this highly concentrated operational risk within the cloud memory division, as highlighted by the following critical factors.
- Relying heavily on $7.75B in cloud memory sales exposes the company to the capital expenditure cycles of hyperscale data centers.
- A sudden reduction in artificial intelligence infrastructure spending would immediately decimate their fastest growing revenue stream.
- The massive costs required to develop high-bandwidth memory mean that any product delays directly destroy overall corporate margins.
All these incredibly complex, highly intertwined risk factors eventually converge on the absolute true measure of executive management efficiency. Achieving a spectacular 30% return on equity vividly demonstrates incredible operational efficiency in rapidly converting corporate capital into massive realized profits. Return on equity accurately measures financial performance by dividing net income by shareholders equity, clearly showing how effectively management uses investment dollars to grow earnings. If these highly unproven physical assets experience minor ramp-up delays, the stunning long-term return profile will fundamentally deteriorate quite quickly.
International headwinds and the final verdict on value investing
The severe trade implication here is that magically maintaining a 30% return on equity will rapidly become mathematically impossible if macroeconomic conditions shift. If the newly constructed manufacturing facilities fail to generate massive operating cash flow, profitability metrics will plummet without warning. This inherent vulnerability brings us smoothly to another crucial financial metric that vividly reveals their deep underlying operational conservatism. This rigid, highly defensive liquidity management strategy inevitably clashes with the steadily rising operational costs of doing massive business internationally.
Adding significantly to this immense operational pressure, the company effective tax rate unexpectedly jumped to a rather frustrating 14.7%. The effective tax rate formally represents the exact average percentage a global corporation actually pays in strict taxes on its total earned income. This 14.7% effective tax rate actually reflects the mandatory and permanent implementation of completely new international minimum tax rules, permanently wiping out previous highly lucrative regional corporate incentives.
For your dynamic stock portfolio, this structural change heavily implies that global headwinds will continue to challenge future profitability. Even with perfectly flawless corporate execution, a much larger portion of their hard-earned operational profits will be systematically siphoned away. Shifting international regulatory environments are proving to be just as dangerous to modern profit margins as traditional cyclical hardware downturns. Investors must actively factor these permanent tax increases into their comprehensive financial models to accurately predict future free cash flow generation.
Successfully navigating these complex international headwinds requires a deep understanding of corporate finance and strict macroeconomic discipline from retail investors. Overlooking a permanent increase in effective tax rates often leads to vastly overestimated future earnings projections in retail valuation models. We strongly encourage readers to look beyond the top-line revenue explosion and focus intently on these hidden international operational costs. Those who critically evaluate both tax liabilities and massive capital expenditures will ultimately build the most resilient and profitable technology portfolios.
Conclusion
The organization has undeniably built a phenomenal, world-class profit engine, yet they are deliberately constructing colossal physical infrastructure that historically triggers devastating industry oversupply. Conducting a thorough Micron stock analysis reveals a fascinating battle between spectacular current operational efficiency and massive future execution risks. I boldly predict this incredibly volatile technology sector will inevitably face a violent, completely unforgiving reversion to the mean within the next 24 months. I want to hear your personal take on whether this massive corporate expansion is pure visionary genius or a rapidly incoming financial disaster, so please let me know in the comments below.
Analyze Nvidia Like a Pro – Get Free 30-Page Professional Report & Insights
Our mission is to provide credible, practical knowledge that helps you make better financial decisions. Each post on this blog is another building block towards your success. We encourage you to read on – the best investment you can make is in your own knowledge.
Disclaimer
This article is provided for informational and educational purposes only and does not constitute investment, financial, or trading advice. The content reflects the author’s opinions and analysis based on publicly available information and does not take into account your individual financial situation, objectives, or risk tolerance. MarketVectors.Pro and its affiliates do not make any representation or warranty as to the accuracy, completeness, or timeliness of the information presented and shall not be held liable for any investment decisions, losses, or damages resulting from the use of this content. Always conduct your own research and consider consulting a qualified financial professional before making any investment decisions. For more details, please review our full disclaimer.
 Did you find this article useful and informative? If it helped you better understand the topic, consider leaving a comment and sharing it with others who might benefit from it. The author is not a licensed financial advisor, and the content is intended for educational purposes only. You can learn more about our mission and team on our about us page. – The MVPro Team



Comments